

Blogs
The revenue trajectory for the China fire sprinkler market demonstrates a robust upward curve, progressing from USD 1,750 million in 2020 to USD 2,680 million in 2025. Sustained market drivers such as urban expansion, regulatory enforcement, and the adoption of smart/eco-friendly sprinkler systems fuel growth. By 2030, revenues are projected to surpass USD 3,750 million, ultimately reaching an estimated USD 4,950 million by 2035. Major contributors include continued investments in commercial infrastructure, retrofitting of aging buildings, and the strengthening of fire safety regulations in metropolitan areas.
Read More - https://bussinessinsights.com/research-report/china-fire-sprinkler-market
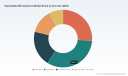
Commercial applications dominate the fire sprinkler market in China as of 2025, reflecting the need for robust fire safety in shopping malls, office towers, and business parks. The residential segment follows closely, spurred by urban apartment developments and government mandates for fire safety systems in new housing. Industrial and warehouse applications further contribute significant market share, supporting China’s extensive manufacturing and logistics activities. Healthcare and institutional segments, while smaller, are emerging growth areas thanks to targeted investments in hospital and educational facility safety.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-fire-sprinkler-market
Frequently Asked Questions
Who are the key players in China Fire Sprinkler Market industry?
Leading players in the China Fire Sprinkler Market include Tyco Fire Protection Products, Johnson Controls, Minimax, Viking Group, and Shanghai Jindun Fire-Fighting Equipment Co., Ltd. These companies drive market innovation, provide comprehensive fire protection solutions, and play significant roles in expanding fire safety infrastructure across commercial and industrial sectors in China.
What is the China Fire Sprinkler Market growth?
The China Fire Sprinkler Market has witnessed robust growth, with a CAGR exceeding 7% during recent years. Rapid urbanization and government regulations have accelerated demand, notably with Johnson Controls expanding smart sprinkler systems and infrastructure to increase market penetration in commercial and industrial buildings.
Which segment accounted for the largest China Fire Sprinkler Market share?
The commercial applications segment accounted for the largest share in the China Fire Sprinkler Market. High-rise office buildings, shopping malls, and large commercial complexes have strict fire safety requirements, driving the adoption of advanced sprinkler solutions and making the sector a key revenue contributor.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting Report: Expandable Microspheres Market to Reach $1,424.94M by 2032, growing at 9.4% CAGR
By PW Consulting, 2026-09-16
Strategic Horizons: The Expandable Microspheres Market to 2032
The global expandable microspheres market has transitioned from a niche materials segment into a strategic enabler of lightweighting, insulation, and sustainable product design. Over the 2020–2025 historical window, revenue climbed from $460.0 million to $759.76 million, reflecting steady industrial adoption across construction, automotive, consumer goods, and specialty coatings. Building on that trajectory, our latest research projects the market to reach $807.5 million in 2026 and to expand to $1,424.94 million by 2032, implying a compound annual growth rate of 9.4 percent. For executives weighing capacity allocation, product portfolio shifts, and supplier partnerships, these figures are not merely benchmarks—they are the starting point for a more rigorous question: which subsegments, geographies, and application vectors will capture disproportionate value as the market matures?
From Baseline to Breakpoint: Why 2026 Is a Decision Year
The forecast period from 2026 through 2032 will be shaped less by uniform expansion than by uneven regulation, input volatility, and targeted product innovation. Recent US trade policy introduced a comprehensive reciprocal tariff framework in 2025, imposing a baseline 10 percent duty on a broad range of chemical imports. That shift alters landed-cost assumptions for feedstocks and finished microspheres, forcing manufacturers and formulators to revisit sourcing mixes and regional production footprints. Simultaneously, European Union regulation now limits microplastic content in rinse-off cosmetics to 0.01 percent, effectively banning conventional polystyrene spheres in facial scrubs and toothpastes. That mandate is narrowing legacy application lanes while elevating demand for compliant, functionally differentiated alternatives. On the input side, petrochemical feedstock prices for benzene and ethylene remain volatile, and the specialized polymer shells and blowing agents central to microsphere production carry escalating cost and workforce requirements. These dynamics do not simply raise costs; they reshape competitive positioning, rewarding firms with integrated supply chains, formulation expertise, and the ability to translate regulation into differentiated product claims.
For strategists, the implication is clear. A single headline CAGR cannot guide resource allocation. The market is fragmenting by performance requirements, compliance thresholds, and regional cost structures. Our report disentangles that complexity by pairing a top-down market trajectory with bottom-up segment logic, enabling teams to test where incremental investment will compound and where exposure should be hedged.
What the Research Delivers for Executive Decision-Making
The Expandable Microspheres Market study is built to serve as a working reference for product, supply chain, and corporate strategy teams. Rather than summarizing public headlines, it structures the market in a way that supports scenario planning, pricing strategy, and go-to-market sequencing. The analysis covers the historical years 2020–2025 and the forecast period 2026–2032, with all monetary values expressed in USD million. The core deliverable includes:
- A full historical-to-forecast revenue series that maps the market’s inflection points against regulatory changes, feedstock cycles, and product introductions, enabling teams to calibrate assumptions for budgeting and planning.
- An application-side view of end-use demand, separating construction, automotive, consumer goods, sports and leisure, and other categories so that growth targets can be tied to realistic adoption curves and formulation economics rather than broad averages.
- A polymer-level assessment of polyacrylic ester, polyvinyl acetate, and vinyl acetate ethylene systems, including relative performance envelopes, processing considerations, and substitution dynamics relevant to lightweighting, insulation, and density reduction.
- A type-based comparison of dry and wet variants, clarifying where each form factor aligns with manufacturing preferences, dispersion requirements, and end-product specifications across composites, paperboard, coatings, and construction materials.
- A regional breakdown that isolates demand concentration, cost exposure, and trade-environment sensitivity across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, supporting sourcing and market-entry decisions.
- Competitive intelligence on core suppliers, including product architecture, application focus, and recent commercialization moves that signal where innovation is redirecting demand.
By connecting segment logic to the macro trajectory, the report gives teams a defensible basis for prioritizing subsegments, selecting pilot applications, and timing capacity or partnership decisions as the 2026–2032 cycle unfolds.
Competitive Architecture: Who Sets the Pace, and Where Gaps Open
The expandable microspheres market remains moderately concentrated, with the top three firms accounting for approximately 62.0 percent of revenue and the top five firms representing roughly 78.0 percent. That concentration reflects the technical barriers associated with polymer shell engineering, blowing-agent formulation, and consistency at scale. Yet concentration does not imply uniform strength across applications or regions. Our research profiles the companies most actively shaping the next phase of demand, including Nouryon in Amsterdam, Nanjing Chemical Material Corp. in Nanjing, Kureha Corporation in Tokyo, Matsumoto Yushi-Seiyaku Co., Ltd. in Yao, Osaka, and Chase Corporation in Westwood, Massachusetts.
Nouryon continues to expand the Expancel® platform across lightweight fillers, blowing agents, and expansion applications in insulation, packaging, construction, automotive, and paperboard uses. Its recent commercialization cadence illustrates how differentiated grades can open adjacent value pools. In April 2026, the company introduced the Expancel® 081 grade at Pulp and Beyond 2026 in Helsinki, enabling a 15–25 percent increase in bulk and thickness in paperboard with up to 1 percent addition. That follow-on to the March 2025 launch of the extra-small Expancel® XS200 grade shows a deliberate push into specialized expansion applications where fine control of particle behavior matters. Earlier, in December 2024, Nouryon introduced the first-generation partially biobased Expancel® BIO microspheres for sustainable construction and automotive uses, signaling a shift toward lower-footprint formulations where end-market claims increasingly matter.
Expandable Microspheres Market
Across the broader field, Nanjing Chemical Material Corp. supplies thermally expandable microspheres focused on lightweighting and density reduction in construction and industrial materials; Kureha Corporation offers thermo-expandable microspheres for closed-cell foaming and lightweight materials in automotive, electronics, and industrial applications; Matsumoto Yushi-Seiyaku Co., Ltd. provides thermo-expandable microspheres for lightweight fillers, blowing agents, and expansion in construction, composites, and industrial uses; and Chase Corporation markets Dualite Expanded Microspheres for insulation, coatings, plastics, and construction applications. The strategic question for buyers and competitors alike is not simply who is largest, but where each firm’s grade architecture, application depth, and regional reach create usable advantage in specific subsegments. Because the market’s value is increasingly tied to formulation performance, compliance fit, and cost structure under shifting trade conditions, our report maps these companies against the segments where their moves matter most, while leaving the precise share and revenue splits for the full analysis.
Regulatory and Input-Price Dynamics: The Hidden Structure of Growth
The 9.4 percent CAGR over 2026–2032 will not be distributed evenly across applications or regions. Growth will be channeled by regulation, feedstock economics, and the pace at which formulators qualify new grades. The US reciprocal tariff posture introduced in 2025 adds a baseline cost layer to chemical imports, complicating cross-border sourcing and encouraging regionalized supply strategies. In parallel, the EU’s 0.01 percent microplastic limit in rinse-off cosmetics is displacing conventional polystyrene spheres in personal-care formats, narrowing a legacy demand lane while redirecting attention toward compliant alternatives and non-cosmetic end uses. On the materials side, benzene and ethylene volatility directly affects styrene-based production economics, while the specialized polymer shells and blowing agents required for microspheres continue to carry cost premiums and workforce sensitivities. Together, these pressures reward companies that can:
- Transition feedstock exposure through formulation adjustments or supply diversification without sacrificing performance consistency.
- Align product claims with emerging compliance expectations, particularly in construction and automotive contexts where sustainability narratives influence specification decisions.
- Segment product lines by performance and cost so that price-sensitive applications can be served without eroding margin in higher-value uses.
- Anticipate regional divergence, where cost structures, tariff exposure, and demand maturity differ enough to require tailored sourcing and positioning strategies.
The report integrates these dynamics into the segment-level narrative, showing how regulation and input volatility are likely to redistribute share and margin potential across types, polymers, end uses, and regions over the forecast window.
Where the Full Intelligence Resides
For teams planning 2026 investments, the headline trajectory is only the entry point. The real decision power lies in understanding how demand is distributed across construction, automotive, consumer goods, sports and leisure, and other end uses; how polymer systems such as polyacrylic ester, polyvinyl acetate, and vinyl acetate ethylene compare on performance and substitution; how dry and wet types serve different processing and dispersion needs; and how regional demand concentration and cost exposure differ enough to shape sourcing and market-entry choices. Our full Expandable Microspheres Market research quantifies those splits, ties them to the 2020–2025 historical record and the 2026–2032 forecast, and overlays competitive moves and regulatory forces so that strategy teams can move from general direction to executable planning.
If your objective is to identify the subsegments with the steepest value capture, calibrate sourcing against tariff and feedstock risk, or anticipate where biobased and specialized grades will reshape specification decisions, the complete dataset and segment logic in the full report are designed to support that work. The macro arc is clear; the advantage will come from knowing exactly where to place capital, formulation effort, and commercial focus as the market advances toward 2032.
Microspheres Market
For detailed analysis of this topic, please visit the official page: Expandable Microspheres Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
China Flexible AC Transmission Systems (FACTS) Market Outlook & Forecast
By supriya singh , 2026-09-16
The revenue for China’s Flexible AC Transmission Systems market has seen a consistent upward trend from 2020 through 2025, rising from $740 Million in 2020 to an estimated $1,195 Million in 2025. This growth is largely attributed to expanding infrastructure investments, policy-driven renewable energy projects, and upgrades of the transmission network. Looking forward, the market is projected to sustain a healthy growth trajectory, reaching approximately $2,800 Million by 2035 as adoption spreads across both urban and rural grids and technological innovation matures further.
Read More - https://bussinessinsights.com/research-report/china-flexible-ac-transmission-systems-(facts)-market
China’s FACTS market in 2025 sees Utilities as the leading application, contributing nearly half of the market demand. Industries, including heavy manufacturing and process plants, represent the second-largest segment as they require robust voltage stability. With the rapid rollout of large-scale wind and solar installations, Renewables Integration takes a significant share, reflecting the critical need for power flow management solutions. The sector is further buoyed by the ongoing electrification initiatives and expansion of smart grid projects, driving strong demand for FACTS across diverse applications.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-flexible-ac-transmission-systems-(facts)-market
Frequently Asked Questions
Who are the key players in China Flexible AC Transmission Systems (FACTS) Market industry?
Key players in the China FACTS market include ABB Ltd., Siemens AG, General Electric (GE), NR Electric Co. Ltd., and Mitsubishi Electric Corporation. These companies are recognized for their technological innovations, comprehensive product portfolios, and significant contributions to advancing grid reliability and efficiency in China's power transmission sector.
What is the China Flexible AC Transmission Systems (FACTS) Market growth?
The China FACTS market has experienced robust growth, driven by grid modernization and increased renewable energy integration. In 2023, NR Electric reported notable contracts for STATCOM installations, reflecting the ongoing investment in transmission upgrades to support renewable integration and bolster grid stability across the country.
Which segment accounted for the largest China Flexible AC Transmission Systems (FACTS) Market share?
The utilities application segment accounted for the largest market share in FACTS adoption. This is due to extensive investments by grid operators in advanced transmission solutions to reduce losses, enhance voltage stability, and accommodate the rising demand for secure and efficient electric power transmission in rapidly expanding urban centers.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
The China 3D and 4D technology market revenue has posted consistent growth since 2020, with a sharp inflection anticipated from 2025, aligning with digitalization and automation trends across key end-user industries. Between 2025 and 2035, annual market revenues are projected to rise from $3,850 Million to over $13,200 Million, highlighting accelerated penetration and investment in advanced manufacturing, digital healthcare, and immersive technologies.
Read More - https://bussinessinsights.com/research-report/china-3d-and-4d-technology-market
In 2025, healthcare commands the largest share of 3D and 4D technology application in China, attributed to rapid medical imaging and bioprinting developments. Entertainment & Media holds the second-largest slice, buoyed by surging demand for 3D content in gaming and film. Industrial use, automotive, and consumer electronics are growing at a steady pace as companies integrate advanced manufacturing and design workflows. The defense segment remains significant as technology supports next-generation simulation and equipment training.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-3d-and-4d-technology-market
Frequently Asked Questions
Who are the key players in China 3D and 4D Technology Market industry?
Key players in China's 3D and 4D technology market include Huawei, Lenovo, Xiaomi, DJI, and Goertek. Huawei leads in advanced imaging solutions; Lenovo integrates 3D/4D in consumer electronics; Xiaomi focuses on AR/VR devices; DJI dominates in 3D mapping drones; Goertek supplies 3D modules for electronics manufacturers.
What is the China 3D and 4D Technology Market growth?
The China 3D and 4D technology market has experienced robust growth, with a CAGR exceeding 15% in recent years. In 2023, companies like DJI reported increased adoption of 3D mapping drones in construction and infrastructure, driving significant market expansion.
Which segment accounted for the largest China 3D and 4D Technology Market share?
The consumer electronics segment held the largest market share in China’s 3D and 4D technology market. Applications such as 3D smartphones, smart TVs, and AR/VR devices, with contributions from industry leaders like Lenovo and Xiaomi, have fueled segment dominance due to high consumer demand.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting: UHF Inlays Market Hits $190M in 2025, Projected to Reach $296.5M by 2032 at 6.5% CAGR
By PW Consulting, 2026-09-16
# Strategic Horizons: Navigating the UHF Inlays Market Evolution (2026-2032)
Executive Summary
The Ultra-High Frequency (UHF) inlays market stands at a pivotal juncture in 2026. As digital transformation accelerates across supply chains, the demand for precise, real-time inventory visibility has moved from a competitive advantage to an operational necessity. Our latest market research provides a comprehensive blueprint for stakeholders looking to capitalize on this trajectory. This article serves as a strategic overview, highlighting the macroeconomic trends, competitive dynamics, and critical industry shifts that define the landscape, while outlining the depth of intelligence available in our full report.
Market Trajectory and Growth Horizons
The financial architecture of the UHF inlays market demonstrates robust resilience and steady expansion. Based on historical performance from 2020 through 2025, the market has consistently outpaced broader industrial averages. The baseline year of 2025 established a significant revenue milestone, reflecting pent-up demand post-pandemic and accelerated adoption in retail and logistics sectors.
Looking forward, the forecast period from 2026 to 2032 projects a compound annual growth rate of 6.5 percent. This growth is not merely linear; it represents a structural shift in how assets are tracked and managed globally. The revenue trajectory suggests that by the end of the forecast window, the market will have substantially doubled its 2020 baseline. Such expansion indicates that UHF inlays are becoming integral to system-level optimization rather than mere accessory components.
For enterprise strategists, understanding this momentum is crucial. The data implies that investment in UHF infrastructure today yields compounded operational benefits over the next half-decade. However, the aggregate growth masks varying pressures across different segments. Our full analysis dissects these nuances without losing sight of the overarching positive trend, ensuring decision-makers understand where the weight of growth is concentrated geographically and thematically.
Industry Dynamics and Technological Shifts
The current landscape is defined by a convergence of regulatory compliance, certification standards, and specialized application requirements. The industry is moving beyond generic tagging toward solution-specific inlays that withstand harsh environments and meet strict retailer mandates.
A significant driver in the healthcare sector involves sterilization compatibility. Recent developments highlight inlays capable of surviving autoclave, gamma irradiation, and ethylene oxide processes. This capability opens new revenue streams in medical device tracking and surgical instrument management, sectors previously hindered by the fragility of standard RFID components. The ability to track items through the entire sterilization process ensures compliance and reduces loss rates in high-value environments.
Simultaneously, the importance of quality certification cannot be overstated. The ARC Quality Certification from the Auburn University RFID Lab has become a benchmark for performance validation. With over 50 billion passive UHF tags deployed globally, retailers and supply chain managers increasingly rely on this certification to ensure read accuracy and interoperability. Compliance with these standards is often a prerequisite for doing business with major global retailers, making certification status a strategic asset for manufacturers and a key evaluation criteria for buyers.
Supply chain efficiency remains the core utility of UHF technology. Real-time inventory tracking facilitates smoother flows from manufacturing to point-of-sale. As labor constraints and operational costs rise, the automation enabled by accurate inlay data becomes a cost-saving lever. The market is seeing a push toward inlays that support simultaneous multi-tag identification and high-speed data transmission, reducing bottlenecks in high-velocity distribution centers.
Rf Eas Label Market
Competitive Landscape Overview
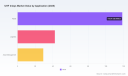
The market structure is moderately fragmented, with concentration ratios indicating room for specialization. The top three players hold a combined market share of 24.6 percent, while the top five control 26.2 percent. This distribution suggests that while incumbents are strong, there is significant activity among mid-tier players and niche specialists who offer targeted value propositions. Success in this environment depends on differentiation through technology, certification, or vertical-specific integration.
Several key entities define the competitive boundaries:
UHF Inlays Market
- Avery Dennison Corporation continues to leverage scale in high-volume RAIN RFID applications. Their focus spans retail, apparel, pharmaceutical, and supply chain domains, with read ranges extending up to 10 meters. Recent product launches targeting sterilization-compatible applications demonstrate their push into specialized healthcare verticals.
- NXP Semiconductors N.V. operates at the chip level, focusing on system-level optimization. Their deep integration with major retailers ensures that their IC technology aligns closely with the requirements of large-scale deployments, influencing the performance standards of the inlays that utilize their semiconductors.
- Impinj, Inc. specializes in endpoint ICs and optimized inlays for connected supply chains. Their emphasis on high read accuracy makes them a critical partner for logistics-heavy operations where missing a tag scan carries significant operational cost.
- Smartrac N.V. maintains a comprehensive portfolio across multiple continents, serving retail, logistics, healthcare, and manufacturing. Their geographic breadth allows them to respond to regional demand shifts effectively.
- Alien Technology LLC addresses cost-sensitive, high-volume supply chain needs. Their semiconductor technology focus positions them well for deployments where margin pressure is high but volume is guaranteed.
- Invengo Technology Pte. Ltd. targets price-sensitive retail and Asia Pacific applications with cost-optimized production of dry inlays. Their manufacturing strategy is tailored to regions where price competitiveness is a primary selection criterion.
- Confidex Ltd. occupies a specialized niche with wet UHF inlays designed for pharmaceutical supply chains and on-metal applications, addressing environments where standard inlays often fail.
- Checkpoint Systems, Inc. and Hana RFID both focus on item-level tagging for apparel and retail, leveraging ARC Quality Certification to validate performance. Hana RFID distinguishes itself with dual manufacturing locations in the USA and China, offering supply chain flexibility.
- Arizon RFID Technology Co., Ltd. has emerged as a notable innovator, particularly with ARC-certified inlays utilizing Impinj series chips. Their recent game-changing product launches focus on long-distance reading and high-speed data transmission for logistics tracking. They also achieved multiple certifications for global supply chain compliance and strengthened their industry standing through academic partnerships.
- Paragon ID and Tageos round out the landscape with focuses on high-volume certification and specialized dual-frequency solutions for security and supply chain applications respectively.
Strategic Implications for Enterprise Decision-Makers
For C-suite executives and supply chain directors, the 2026 market context requires a shift from tactical purchasing to strategic procurement. The choice of inlay partner impacts not just immediate costs, but long-term system interoperability and compliance status.
First, the varying market shares by region suggest that global rollouts require localized partner strategies. While some providers dominate in North America, the growth dynamics in Asia Pacific and Europe require different competencies. A supplier strong in retail apparel may not be optimal for industrial logistics.
Second, the divergence between dry and wet inlays technology matters for application engineering. Dry inlays offer cost advantages in standard paper-based or synthetic label applications, particularly in retail. Wet inlays provide durability and adhesive properties necessary for on-metal or harsh chemical environments. Selecting the wrong type can lead to read failures and increased total cost of ownership.
Third, application-specific ROI varies significantly. Retail item-level tagging drives high volume, but logistics and asset management offer different value propositions regarding loss prevention and throughput. Understanding the revenue contribution of each application helps in forecasting demand and aligning internal budgets with external market reality.
Inside the Full Report: Deliverables and Actionable Intelligence
To support these strategic decisions, our comprehensive market research study offers granular data and analytical frameworks that go beyond the macro trends discussed here. The full report is designed to function as a decision support system for procurement, R&D, and market entry strategies.
Key components of the research include:
- Historical and Forecast Revenue Analysis: A year-by-year breakdown of market size from 2020 through 2032, validating the 6.5 percent CAGR assumption and identifying inflection points in adoption curves.
- Regional Performance Metrics: Detailed revenue distributions across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, allowing for precise geographic budgeting and market prioritization.
- Type and Application Segmentation: In-depth splits between Dry and Wet inlays, as well as revenue contributions from Retail, Logistics, and Asset Management sectors. This data enables companies to benchmark their product mix against the broader market equilibrium.
- Competitive Profiling: Extended profiles for all key companies, including headquarters, product focus, URLs, and strategic positioning. This section helps identify potential partners, competitors, or acquisition targets.
- Recent Developments Tracking: A chronology of product launches, certifications, and partnerships from early 2025 through early 2026. This ensures stakeholders are aware of the latest technological thresholds and compliance requirements entering the market.
- Market Concentration Data: Precise concentration ratios and analysis of the fragmented tiers below the top players, providing insight into competitive intensity and potential consolidation opportunities.
Our methodology ensures that every data point is contextualized within industry dynamics. We do not simply report numbers; we interpret what those numbers mean for supply chain resilience, cost structures, and technology roadmaps.
Conclusion
The UHF Inlays Market in 2026 is characterized by steady growth, technological specialization, and increasing regulatory rigor. The projected expansion to over 296 million USD by 2032 underscores the sector's viability as a long-term investment area. However, navigating the nuances of regional demand, inlay types, and competitive certifications requires more than high-level trends. It demands precise intelligence.
This article has outlined the strategic landscape, highlighting the importance of sterilization compatibility, ARC certification, and supply chain efficiency. Yet, to fully leverage these insights for specific business outcomes, organizations need the detailed segmentation data and competitor benchmarks contained in the full study. The difference between a good strategy and a great one often lies in the details of market share distribution and application-specific growth rates, which our comprehensive report provides.
For stakeholders ready to deepen their market intelligence and secure a competitive edge in the UHF RFID ecosystem, the complete dataset offers the clarity needed to move from observation to action. The market is growing, but the winners will be those who understand exactly where the growth is happening and who is leading it.
For detailed analysis of this topic, please visit the official page: UHF Inlays Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The China Ultraviolet Analyzer Market is poised for notable expansion with revenues projected to increase from $453 million in 2020 to approximately $1,145 million by 2035, reflecting a compound annual growth rate of around 6.5%. This upward trajectory is attributed to increased investments in environmental infrastructure, rising adoption across various industries, and a steady stream of technological innovation. Significant revenue increments are expected especially during 2027–2031 as several government-led green and safety initiatives materialize.
Read More - https://bussinessinsights.com/research-report/china-ultraviolet-analyzer-market
By application, water quality monitoring is expected to dominate the China Ultraviolet Analyzer Market in 2025, accounting for the highest share as municipal and industrial demands surge under new regulatory mandates. Chemical analysis follows, underpinned by the chemical sector's modernization, while environmental monitoring is increasingly relevant given green initiatives. The food and beverage and pharmaceutical analysis segments are also growing rapidly as producers seek rapid, non-destructive testing solutions to ensure safety and compliance.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-ultraviolet-analyzer-market
Frequently Asked Questions
Who are the key players in China Ultraviolet Analyzer Market industry?
Key players in the China Ultraviolet Analyzer Market include Thermo Fisher Scientific, Shimadzu Corporation, ABB Ltd, Hach Company, and Focused Photonics Inc (FPI). These companies lead the market with advanced analytical technologies, strong distribution networks, and innovative UV analyzer solutions tailored for environmental, industrial, and research applications.
What is the China Ultraviolet Analyzer Market growth?
The China Ultraviolet Analyzer Market is experiencing robust growth, driven by increasing environmental monitoring regulations and demand for improved analytical tools. For instance, Thermo Fisher Scientific has reported increased sales in UV analyzers, attributing growth to stricter pollution control policies and industrial upgrades in China.
Which segment accounted for the largest China Ultraviolet Analyzer Market share?
The environmental monitoring segment accounted for the largest market share in the China Ultraviolet Analyzer Market. Applications such as air and water quality analysis are in high demand due to regulatory focus, prompting significant investments from local governments and industries to deploy advanced UV analyzers for compliance.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting: Rheology Modifiers Market Hits $11.45B in 2025, Poised to Reach $15.27B by 2032
By PW Consulting, 2026-09-16
The Rheology Modifiers Market in 2026: Navigating Growth, Compliance, and Competitive Complexity
Executive Overview
The global rheology modifiers market has entered a decisive phase of structural expansion, shifting from a period of steady organic growth to one defined by regulatory pressure, raw material volatility, and accelerated formulation innovation. With a 2025 baseline valuation of USD 11.45 billion and a projected valuation of USD 12.17 billion at the close of 2026, the market is on a clear trajectory toward USD 15.27 billion by 2032. At a compound annual growth rate of 4.2 percent across the forecast window, the sector is no longer moving at the pace of incremental capacity additions or routine product refreshes. It is being reshaped by the simultaneous forces of sustainability mandates, performance-driven reformulation, and strategic supply chain repositioning.
For market participants, 2026 is not a simple continuation of historical momentum. It is a year in which segmentation decisions, geographic prioritization, and product portfolio alignment will determine which firms capture disproportionate value and which face margin compression from compliance costs and feedstock uncertainty. The latest Rheology Modifiers Market research from PW Consulting has been built to equip strategic decision-makers with the analytical rigor required to navigate this environment. This article outlines the strategic architecture of the study and explains why its findings should be treated as essential input for 2026 planning cycles.
From Steady Expansion to Structural Realignment: Why 2026 Is a Deviation Year
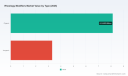
The historical record from 2020 through 2025 reveals more than a smooth revenue curve. It documents a market that absorbed pandemic-era disruptions, navigated supply bottlenecks, and successfully scaled production to support a rising demand base across coatings, personal care, adhesives, and specialty industrial applications. The journey from USD 9.32 billion in 2020 to USD 11.45 billion in 2025 reflects both volume growth and the increasing technical deployment of rheology modifiers in formulations where viscosity control, suspension stability, and application behavior directly influence end-product performance and regulatory compliance.
Yet the forecast period introduces a more nuanced picture. Growth through 2032 will not be evenly distributed across all segments, nor will it be immune to external pressure points. The forecast profile shows a market that continues to expand but also encounters inflection points tied to regulatory alignment, raw material cost structures, and regional manufacturing footprints. A 4.2 percent CAGR may appear moderate in isolation, but in a market of this scale and technical complexity, it implies substantial absolute value creation and intensifying competition for high-growth pockets within paints and coatings, personal care, and emerging bio-based formulation pathways.
This is precisely why the research has been designed not merely as a top-line forecast tool, but as a decision framework for 2026. Firms that treat 2026 as a year of routine execution risk misallocating R&D, production capacity, and commercial resources. Firms that use the study to anticipate segment acceleration, regional demand migration, and formulation shifts will be better positioned to act before market signals become obvious.
What the Study Delivers: Actionable Intelligence Beyond the Headline Numbers
The full report is structured to translate macro trajectory into operational guidance. It begins with the historical baseline and forward projection, but its greater value lies in the depth of its segmentation logic, competitive mapping, and scenario-ready insights. Decision-makers can expect to access an integrated analysis that connects market size evolution to the underlying demand drivers, formulation trends, and regional dynamics that will shape procurement strategies, capacity investment decisions, and product roadmap planning throughout the forecast horizon.
Rheology Modifiers Market
Specifically, the study addresses several dimensions that are often fragmented across separate analyses:
- A detailed review of market structure by type, including the relative positioning of organic and inorganic rheology modifier categories and their respective relevance to formulation requirements across major end-use industries.
- An application-level reading of demand concentration, highlighting where rheology modifiers are gaining share in core uses and where technical or regulatory friction is reshaping adoption velocity.
- A regional assessment that identifies where mature demand bases are stabilizing and where growth momentum is accelerating due to manufacturing expansion, regulatory transitions, and formulation modernization.
- An evaluation of market concentration and competitive intensity, offering context on how consolidated the landscape is and what that means for pricing behavior, differentiation, and supplier negotiation.
- A review of recent corporate developments, including product launches and capacity expansions, that signal where leading players are betting on future demand.
The report also integrates the external factors that are increasingly inseparable from market forecasts. Feedstock dynamics tied to crude oil price movements, evolving restrictions on synthetic polymer microparticles, VOC-related formulation shifts, and compliance demands linked to REACH, FDA, and food-contact considerations are addressed as market-shaping variables rather than peripheral noise. That means the analysis does not simply project demand; it places demand within the regulatory and cost environment that executives must actually manage.
Competitive Positioning: Where Leading Players Are Investing and Innovating
The competitive landscape is defined by a concentrated group of globally active chemical and specialty materials firms, each competing on technical performance, application specificity, regional presence, and sustainability alignment. The research provides a structured competitive scan of these players, with a focus on how product portfolios are being tailored to water-based, solvent-based, and solvent-free formulations, and how recent moves suggest broader strategic intent.
Among the firms profiled, BASF SE continues to build on a broad rheology modifier platform spanning RHEOVIS®, ATTAGEL®, ATTAFLOW®, and EFKA® products, with a clear emphasis on serving water-based, solvent-based, and solvent-free applications. The April 2025 announcement of a production line expansion for Rheovis HEUR thickeners in Nanjing, China signals a deliberate response to rising demand from architectural and industrial coatings markets. This type of capacity action is significant because it links product availability directly to regional growth dynamics rather than treating supply as a generic global function.
The Dow Chemical Company maintains a focused presence through ACRYSOL™ HASE rheology modifiers and PRIMAL™ RM-7 for latex coatings, positioning itself where performance consistency in latex-based systems remains a priority. Lubrizol Corporation is expanding in personal care and specialty Formulation through Solthix™ and Carbopol® rheology modifiers, and its May 2025 introduction of Arbalon® RC 76 cellulose liquid illustrates a continued push into cationic cellulose-derived solutions for personal care applications. These moves suggest that leading suppliers are not only defending core positions but also refining portfolios toward higher-value formulation niches.
Other major participants reflect similarly differentiated strategies. Elementis plc brings RHEOLATE® associative polyurethane thickeners and BENTONE® clay-based modifiers into competition, while Evonik Industries AG relies on AEROSIL® fumed silica and the TEGO® ViscoPlus series to articulate a performance-led value proposition. Clariant AG maintains a prominent personal care and coatings footprint with Hostagel™ and Aristoflex® lines, and its August 2025 launch of Aristoflex SUN underscores a recent focus on advanced sunscreen formulations with improved stability and SPF performance. Ashland Global Holdings Inc. continues to compete through Aquaflow™ nonionic synthetic associative thickeners and Natrosol® cellulosic products, reinforcing the breadth of its formulation support capabilities.
The competitive scan also includes firms that are shaping regional and application-specific demand with notable precision. Croda International Plc emphasizes high-performance rheology modifiers for aqueous and non-aqueous formulations. Münzing Chemie GmbH contributes TAFIGEL® PUR alongside HEUR/HASE associative modifiers. BYK-Chemie GmbH is active with fumed silica-based and associative additives. Arkema S.A. extends its offering with Coapur® and Rheostyl® waterborne modifiers. AkzoNobel N.V. competes in coatings and industrial applications with formulation-specific rheology solutions. San Nopco Co. rounds out the landscape with its SN-Thickener series polymer and associative modifiers. Taken together, these players illustrate that the market is not a simple contest of scale; it is one where technical differentiation, application specificity, and regional readiness increasingly determine commercial advantage.
The Regulatory and Cost Environment Reshaping Demand Signals
A defining feature of the 2026 outlook is that demand is being steered as much by compliance as by performance. In North America, EPA VOC limits for architectural coatings are accelerating the shift toward waterborne rheology modifiers with lower solvent content. This transition favors suppliers that can deliver effective thickening and suspension in waterborne systems without compromising application characteristics or dry-time behavior. In Europe, EU Regulation 2023/2055 on synthetic polymer microparticles is placing new constraints on certain associative thickeners, increasing the pull toward bio-based alternatives and more sustainable formulation architectures. At the same time, stringent restrictions on APEO-containing thickeners in both the EU and North America are pushing reformulation efforts toward options that satisfy environmental expectations while preserving performance.
Beyond regulation, raw material dynamics remain a critical planning variable. Volatility in crude oil prices directly influences feedstock costs for synthetic acrylic and polyurethane rheology modifiers used in coatings, making cost forecasting and formulation flexibility more important than ever. Meanwhile, escalating technical complexity across REACH and FDA compliance for food-contact applications means that product qualification cycles can become longer and more demanding. These factors do not eliminate growth; they reshape where growth is achievable and which suppliers can serve it efficiently.
This is why the research treats regulatory and feedstock conditions as integral inputs to the forecast environment rather than as disconnected background events. The analysis connects these pressures to operational implications: what they mean for reformulation roadmaps, how they alter the attractiveness of different product types, and where regional demand may shift as end-users adapt to new compliance realities.
Why the Study Is Strategic Input for 2026 Decision-Making
For executives, procurement leaders, R&D directors, and strategy teams, the value of this study lies in its ability to convert market trajectory into decision-ready context. In a market projected to rise from USD 11.45 billion in 2025 to USD 12.17 billion in 2026, and onward toward USD 15.27 billion by 2032, the immediate question is not whether growth exists. The question is where the most defensible growth will originate, which segments will face the steepest technical or regulatory barriers, and how competitive intensity will evolve as leading players align capacity and product portfolios with regional demand shifts.
Worldwide Rheology Modifier Coating Additive Market
The report is designed to support that decision process by clarifying the structural forces behind the numbers. It helps teams evaluate whether current portfolio exposure aligns with the fastest-moving application areas, assess which type categories are likely to gain relevance under evolving formulation and compliance conditions, and understand how regional dynamics may influence sourcing, production, and market-entry priorities. It also provides a competitive baseline that makes it easier to interpret new product launches, capacity announcements, and partnership activity as signals rather than isolated events.
In practical terms, the study supports a range of 2026 uses:
- Refining segment-level growth assumptions before committing to capacity, inventory, or commercial investment.
- Identifying formulation trends that may alter demand for organic versus inorganic rheology modifiers across core applications.
- Anticipating regional shifts tied to regulatory transitions and manufacturing expansion.
- Benchmarking competitive positioning against major global suppliers with differentiated product systems and recent market moves.
- Integrating regulatory and raw material risk into longer-term market planning rather than treating them as after-the-fact constraints.
Conclusion: Treat 2026 as a Year for Informed Strategic Positioning
The rheology modifiers market is entering 2026 with solid momentum, but also with heightened complexity. Growth is real, yet it is increasingly selective. Regulatory evolution is accelerating formulation change, feedstock volatility is complicating cost planning, and competitive players are responding with targeted capacity expansion and application-specific innovation. In this environment, broad market awareness is no longer enough. Decision-makers need a structured, evidence-based view of where value will be created, which segments will be most affected by external pressures, and how the competitive field is shifting beneath the headline numbers.
The full Rheology Modifiers Market research from PW Consulting provides that view. It combines historical context, forward-looking projections, segmentation insight, competitive profiling, and industry-context analysis into a single strategic framework intended for 2026 planning and beyond. The complete report contains the segmented detail, regional interpretation, application-level analysis, and executive recommendations necessary to turn market intelligence into action. For teams preparing for a year in which strategic precision matters more than ever, the research offers the depth required to move from observation to execution.
For detailed analysis of this topic, please visit the official page: Rheology Modifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Truck-Bus Tire Market Hits $209.2M in 2025, Projects 5.3% CAGR to $301.7M by 2032
By PW Consulting, 2026-09-16
Strategic Outlook: Navigating the Truck-Bus Tires Market in 2026 and Beyond
Executive Summary
The commercial transportation sector stands at a critical inflection point. As global supply chains recalibrate and regulatory frameworks tighten, the Truck-Bus Tires Market represents a vital component of operational efficiency and cost management for fleet operators. Our latest market research provides a comprehensive strategic compass for navigating this complex landscape through 2032. This report is not merely a collection of statistics; it is a decision-making tool designed to identify risks, uncover growth vectors, and optimize procurement strategies in an increasingly volatile environment.
For strategic planners and procurement leaders, understanding the trajectory of this market is essential. The data indicates a sustained period of growth driven by replacement demand, fleet modernization, and regulatory compliance requirements. However, the margin for error is narrowing. Fluctuating raw material costs, shifting trade policies, and the rapid adoption of alternative powertrains require a nuanced approach to forecasting and inventory management. This article outlines the strategic value of our upcoming analysis, highlighting key market dynamics, competitive forces, and operational challenges that define the current era.
Long-Term Market Trajectory and Growth Drivers
Analyzing the historical performance from 2020 through 2025 provides a foundational understanding of market resilience. The sector has demonstrated consistent expansion, overcoming pandemic-induced disruptions to reach significant valuation milestones. Our forecast period, spanning from 2026 to 2032, projects a continued upward trend, underpinned by a steady compound annual growth rate. This growth is not uniform; it is propelled by specific macroeconomic engines that organizations must monitor closely.
The expansion is largely fueled by the necessity of maintaining operational continuity. As existing vehicle fleets age, the replacement cycle intensifies, ensuring steady demand even when new vehicle production fluctuates. Furthermore, the push towards heavier goods transportation and increased freight volumes across key economic zones contributes to higher tire consumption rates. Organizations that align their inventory planning with these long-term growth trajectories will be better positioned to manage supply chain bottlenecks and capitalize on emerging market opportunities.
Key elements influencing this trajectory include:
- Infrastructure development projects that increase heavy commercial vehicle movement.
- Rising logistics demand in emerging economies requiring robust transport solutions.
- The transition towards higher durability products that last longer but cost more upfront.
- Regulatory pressures forcing fleets to upgrade to compliant tire specifications.
Critical Market Dynamics and Operational Shifts
The landscape is being reshaped by external forces that directly impact production costs and consumer behavior. In the current environment, raw material volatility is a primary concern. Recent industry data highlights significant spikes in natural rubber prices, which have surged substantially over short periods. Since raw materials now comprise a dominant portion of production expenses, manufacturers are facing pressure to adjust pricing structures or absorb costs to maintain market share. This volatility creates uncertainty for downstream buyers who need to budget for long-term contracts.
Regulatory environments are equally transformative. Strict efficiency mandates from bodies such as the United States Environmental Protection Agency are compelling fleet owners to transition toward low-rolling-resistance radial products. This shift is not optional; it is a compliance requirement that directly influences purchasing decisions. Furthermore, trade policies have introduced new cost layers. Recent surges in steel tariffs have contributed to higher costs for imported components, affecting the final price point of tires available in key markets. These macroeconomic variables must be integrated into financial modeling to avoid budget overruns.
The electrification of commercial fleets is another pivotal dynamic. Industry reports indicate that a significant portion of new buses exceeding certain weight classes registered recently were partially or fully electrified. This transition drives demand for sustainable tire solutions designed to handle the unique torque and weight characteristics of electric vehicles. As the powertrain mix changes, the specifications required for optimal performance evolve, creating a niche for specialized tire technologies that support sustainable transportation goals.
- Raw material scarcity leading to price instability and production delays.
- Government mandates accelerating the adoption of fuel-efficient tire technologies.
- Trade policy changes impacting the cost structure of imported goods and steel components.
- Electrification trends requiring specialized tire formulations for electric commercial vehicles.
Segmentation Insights: Type and Application Trends
Understanding the structural composition of the market is vital for targeted strategy development. The market is primarily divided by tire construction type and vehicle application. In terms of type, the radial segment continues to dominate the landscape, reflecting the industry's broad shift towards higher performance and fuel efficiency. While bias tires maintain a presence, particularly in specific regional or heavy-load applications, the momentum is clearly behind radial technology. Our analysis delve into the specific volume splits within these categories, revealing where the highest growth margins are located.
Regarding application, trucks constitute the larger portion of the market volume compared to buses, driven by the sheer scale of freight logistics globally. However, the bus segment is experiencing unique pressures due to urban mobility initiatives and the electrification trends mentioned earlier. Fleet managers must recognize that while the truck segment offers volume, the bus segment may offer faster adoption rates for new technologies. Detailed segmentation data allows organizations to allocate resources effectively, focusing on the high-growth niches rather than treating the market as a monolith.
Strategic implications of these segments include:
- Prioritizing radial tire procurement to meet efficiency standards and reduce total cost of ownership.
- Monitoring truck replacement cycles for steady revenue streams and supply planning.
- Evaluating bus fleet electrification plans to anticipate demand for specialized electric-compatible tires.
- Assessing regional preferences where bias tires may still retain relevance due to road conditions or cost constraints.
Regional Performance and Supply Chain Considerations
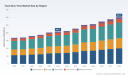
Geographic dynamics play a crucial role in supply chain strategy. The market is broad, with significant volume distributed across multiple continents. North America and Asia Pacific represent substantial portions of the market size, reflecting the heavy industrialization and freight movement in these regions. Europe maintains a strong presence driven by stringent environmental regulations and dense logistics networks. Meanwhile, Latin America and the Middle East and Africa offer emerging opportunities that are often overlooked in generalized analyses.
For multinational operators, understanding these regional weights is not about simple market sizing but about risk diversification. Dependence on a single region for supply or demand can be disruptive. Our research provides a granular look at these regional contributions without oversimplifying the nuances. Supply chain managers need to know where production hubs are vulnerable and where demand is most resilient. This geographic intelligence supports decisions on warehousing, logistics partnerships, and localized manufacturing investments.
Regional strategic focus areas include:
- Strengthening supply chain resilience in high-volume regions like North America and Asia Pacific.
- Navigating regulatory landscapes in Europe to ensure compliance with efficiency mandates.
- Exploring growth potential in emerging markets where infrastructure investment is accelerating.
- Mitigating tariff impacts by evaluating local sourcing options versus imported solutions.
Competitive Landscape and Company Strategies
The market is characterized by high concentration, with a few key players controlling a significant majority of the share. This consolidation means that competitive moves by top-tier manufacturers ripple through the entire ecosystem. Our report profiles major industry leaders, analyzing their specific offerings, headquarters locations, and strategic focus areas. Companies such as Michelin and Bridgestone continue to set benchmarks with their comprehensive lines of commercial tires emphasizing safety and cost-effectiveness.
Competitors on the periphery, such as Goodyear and Continental, are also aggressively innovating. Continental, for instance, has been particularly active, appointing new leadership for original equipment roles and releasing new product catalogs. Their focus on sustainability certification and product size extensions demonstrates a commitment to adapting to fleet needs and environmental standards. Other significant players like Apollo Tyres, JK Tyre, and BKT are expanding their footprints, particularly in international markets, offering wide ranges of tires for urban to long-haul operations.
Tire Market
The competitive environment is not static. Recent developments show companies launching specific products for regional fleets and expanding size offerings to cover more vehicle types. Hankook and Giti Tire are also notable for their high-quality offerings for trucks, buses, and commercial vans. Understanding the product roadmaps of these competitors allows businesses to benchmark their own requirements and negotiate better terms with suppliers who are competing for contract retention.
- Monitoring product launches and size extensions from leaders like Michelin, Bridgestone, and Continental.
- Tracking sustainability initiatives and certifications that may become procurement criteria.
- Analyzing the expansion strategies of emerging competitors like Apollo, JK Tyre, and Hankook.
- Identifying leadership changes within key companies that signal shifts in strategic direction.
Strategic Imperatives for 2026 Decision Makers
As organizations plan for the remainder of the decade, several imperatives emerge from the data. First, cost management must be dynamic. With raw material expenses comprising a large share of production costs and trade tariffs fluctuating, static budgeting is insufficient. Procurement teams need flexible contracts that account for material volatility. Second, technology adoption cannot be delayed. The shift toward low-rolling-resistance and electric-compatible tires is accelerating due to regulation and fleet electrification. Early adoption can secure compliance advantages and operational efficiencies.
Third, supply chain diversification is critical. Given the concentration of market share among top players and the geopolitical factors affecting trade, relying on a single supply source is risky. Building relationships with multiple tier suppliers across different regions can buffer against disruptions. Finally, sustainability is becoming a procurement metric. As certification and environmental standards tighten, tires are no longer just rubber components but part of a broader sustainability strategy. Aligning tire procurement with corporate sustainability goals will be increasingly important for public and private fleet operators.
- Implement dynamic pricing models to handle raw material cost fluctuations.
- Accelerate the transition to compliant radial and electric-ready tire technologies.
- Diversify supplier bases to mitigate regional risks and tariff impacts.
- Integrate tire sustainability metrics into broader corporate environmental goals.
Unlock Full Market Intelligence
This overview provides the strategic context necessary to understand the magnitude of the opportunity and the complexity of the challenges facing the Truck-Bus Tires Market. However, successful execution requires depth. To make informed decisions that withstand the volatility of the coming years, leaders need access to granular data, specific segmentation splits, and detailed competitive profiles. Our full report contains the precise valuations, regional percentages, and company-specific forecasts that allow for precise planning.
We invite strategic leaders to access the complete research document to gain the actionable intelligence required to optimize fleet performance, manage costs, and capture growth in the 2026 to 2032 period. The market is moving fast, and the insights within our full analysis are designed to keep your strategy ahead of the curve.
Truck-Bus Tires Market
For detailed analysis of this topic, please visit the official page: Truck-Bus Tires Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The China Inductor Market demonstrates steady revenue growth from USD 2,780 Million in 2020, reaching USD 4,150 Million by 2025. This momentum is forecast to continue at an 8.9% CAGR, positioning the market to surpass USD 10,210 Million by 2035. The growth reflects accelerating demand from automotive, telecommunications, and consumer electronics. The period between 2025 and 2030 is anticipated to witness the steepest incline, coinciding with the widescale deployment of electric vehicles and next-generation communications networks.
Read More - https://bussinessinsights.com/research-report/china-inductor-market
The consumer electronics segment leads the China Inductor Market in 2025, making up the highest percentage of demand, influenced by strong production of smartphones, tablets, and wearables. Automotive applications are the next largest, propelled by rapid electrification within the vehicle sector. Telecommunications ranks third, driven by robust 5G infrastructure rollout. The share from industrial, healthcare, and aerospace & defense remains significant but notably smaller, highlighting a focused application landscape in high-volume and high-tech sectors.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-inductor-market
Frequently Asked Questions
Who are the key players in China Inductor Market industry?
The top 5 key players in the China Inductor Market include TDK Corporation, Murata Manufacturing, Taiyo Yuden, Shenzhen Sunlord Electronics, and Chilisin Electronics. These companies drive market innovation by offering a wide range of inductor products used in automotive, consumer electronics, and industrial applications.
What is the China Inductor Market growth?
The China Inductor Market has experienced robust growth, with an estimated CAGR of over 6% from 2021 to 2024. Recent expansions by Murata Manufacturing and TDK Corporation, driven by increased demand in 5G infrastructure and electric vehicles, have contributed significantly to this upward trend.
Which segment accounted for the largest China Inductor Market share?
The consumer electronics segment holds the largest share in the China Inductor Market. The widespread use of smartphones, tablets, and smart home devices, manufactured by leading brands like Huawei and Xiaomi, continues to fuel inductor demand, making this application segment the market leader.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting: Traumatic Brain Injury Diagnostic Market to Hit $769.94M by 2032 at 12.7% CAGR
By PW Consulting, 2026-09-16
Navigating the Brain: Strategic Intelligence in the Traumatic Brain Injury Diagnostic Market (2026-2032)
The landscape of traumatic brain injury (TBI) diagnostics is undergoing a profound transformation, shifting from reliance on subjective clinical assessments and structural imaging toward objective, biomarker-driven, and AI-enhanced diagnostic paradigms. As healthcare systems grapple with the long-term neurological consequences of mild TBI and concussion, the demand for rapid, accurate, and accessible diagnostic tools has never been more critical. For executive leadership, investors, and strategic planners operating in the medical technology and life sciences sectors, understanding the trajectory of this market is not merely an academic exercise—it is a commercial imperative. Our latest comprehensive market research report, covering the historical baseline from 2020 through the forecast horizon to 2032, offers a detailed roadmap of this evolving ecosystem. This article serves as a strategic preview, illustrating the macroeconomic currents, technological inflection points, and competitive dynamics that will define decision-making in 2026 and beyond.
Executive Summary: The Scale and Trajectory of a High-Growth Diagnostic Sector
The global market for TBI diagnostics has demonstrated consistent and accelerating expansion over the past half-decade. Valued at approximately 245.34 million USD in 2020, the market has grown steadily to reach an estimated 335.15 million USD by 2025. This historical progression reflects the gradual but firm integration of novel diagnostic modalities into emergency departments, sports medicine clinics, and specialized neurological care pathways. Looking forward, the sector is projected to maintain a robust compound annual growth rate of 12.7 percent throughout the 2026 to 2032 forecast period. By 2032, the total market revenue is anticipated to approach 769.94 million USD. Such a trajectory underscores a market that is not only expanding in absolute terms but is also maturing in its technological complexity and clinical adoption rates. For corporate strategists, these figures signal a window of opportunity where early positioning, strategic partnerships, and targeted product development can yield disproportionate competitive advantages. The growth is not uniform across all vectors; rather, it is being propelled by specific technological breakthroughs, regulatory clearances, and shifting clinical guidelines that prioritize objective diagnostic confirmation over empirical judgment.
Technological Convergence: Imaging, Biomarkers, and Digital Diagnostics
The architecture of the TBI diagnostic market is defined by a compelling convergence of established imaging technologies and emerging biological and digital assessment tools. Traditional structural imaging, primarily computed tomography and magnetic resonance imaging, has long served as the cornerstone for identifying acute intracranial lesions. However, the diagnostic gap for mild TBI and concussion, where structural abnormalities often remain invisible, has catalyzed innovation in blood-based biomarker assays and neurophysiological monitoring platforms. The market now features a dynamic interplay between these modalities. Blood-based biomarker tests, which detect proteins such as glial fibrillary acidic protein and ubiquitin carboxy-terminal hydrolase L1, offer the promise of rapid, objective triage that can potentially reduce unnecessary imaging referrals and accelerate clinical decision-making. Complementing these biological assays is a new generation of AI-enabled platforms that analyze electroencephalographic patterns, eye-tracking metrics, and multimodal data streams to provide prognostic insights and severity grading. This technological diversification is reshaping procurement strategies, clinical workflows, and reimbursement models. Healthcare providers are increasingly evaluating integrated diagnostic suites rather than standalone devices, while device manufacturers are pursuing cross-platform compatibility and data interoperability to secure long-term market relevance.
Regulatory Catalysts and Clinical Validation: Accelerating Market Readiness
Regulatory milestones have emerged as a critical accelerant for commercialization and clinical adoption in the TBI diagnostics space. Over the past several years, a series of landmark clearances and certifications have validated the clinical utility of biomarker and digital diagnostic tools, providing a regulatory scaffold upon which broader market confidence is being built. The clearance of whole blood testing cartridges for point-of-care biomarker assessment, alongside serum-based automated platforms for ruling out intracranial lesions, has expanded the addressable clinical settings beyond centralized laboratories. Concurrently, digital health devices utilizing eye-movement analysis and AI-driven electroencephalography have secured clearances with increasingly broad labeling indications, enabling objective concussion assessment across diverse age groups and post-injury timeframes. These regulatory achievements are not merely compliance checkpoints; they are market-making events that influence purchasing decisions, insurance coverage trajectories, and clinical guideline updates. Furthermore, ongoing pivotal clinical studies continue to generate the evidence base required to support expanded indications, prognostic claims, and integration into standard-of-care protocols. For market participants, tracking the cadence of regulatory approvals and clinical trial readouts is essential for anticipating shifts in competitive positioning and identifying whitespace opportunities for product iteration or strategic entry.
Competitive Landscape: Specialized Innovators and Diversified Incumbents
The competitive fabric of the TBI diagnostic market is characterized by a blend of focused innovators and broad-based healthcare conglomerates, each pursuing distinct strategic pathways to capture value. A cohort of specialized companies has emerged at the forefront of biomarker and digital diagnostic development, leveraging proprietary assays, algorithmic platforms, and niche clinical expertise to differentiate their offerings. These firms are actively expanding their intellectual property portfolios, advancing pivotal clinical trials, and strengthening commercial leadership to scale their technologies from research and pilot deployments into broader clinical practice. Simultaneously, major diagnostic and life sciences corporations are integrating TBI diagnostic capabilities into their existing immunoassay, point-of-care, and clinical chemistry portfolios, leveraging established distribution networks, regulatory experience, and commercialized product platforms to accelerate market penetration. The result is a landscape where innovation speed, clinical evidence generation, and supply chain robustness are equally vital. Market concentration remains relatively moderate, reflecting the early-stage fragmentation of advanced diagnostic modalities and the ongoing validation of new clinical workflows. This structural characteristic suggests that consolidation, licensing arrangements, and strategic collaborations will likely play an increasingly prominent role as the market matures and clinical adoption curves steepen.
Key organizations shaping the competitive dynamics include:
- Banyan Biomarkers, Inc. – Pioneering blood-based biomarker assays targeting GFAP and UCH-L1 to support mild TBI evaluation and inform imaging triage decisions.
- BrainBox Solutions, Inc. – Developing AI-enabled multi-modality diagnostic and prognostic platforms for concussion and mild TBI, with active advancement of pivotal clinical studies and patent portfolio expansion.
- Oculogica, Inc. – Commercializing eye-tracking diagnostic devices that provide objective, baseline-free concussion assessment across broad pediatric and adult age ranges.
- BrainScope Company, Inc. – Advancing AI-powered electroencephalography-based brain assessment platforms for objective evaluation of mild TBI and concussion as an adjunct to standard clinical practice.
- Quanterix Corporation – Utilizing ultra-sensitive digital immunoassay architectures to support biomarker quantification for TBI-related diagnostic applications.
- bioMérieux – Integrating automated serum-based biomarker testing into clinical microbiology and immunoassay portfolios, with cleared indications for ruling out intracranial lesions in mild TBI.
- ABBOTT – Deploying point-of-care whole blood testing cartridges for rapid biomarker assessment, enabling bedside evaluation and streamlined emergency department workflows.
- Upfront Diagnostics – Focusing on lateral flow assay technologies for point-of-care detection of brain injury biomarkers as a diagnostic adjunct in decentralized care settings.
Demand Drivers: Emergency Care, Sports Medicine, and Defense Applications
Clinical demand for TBI diagnostics is being generated across multiple care settings, each with distinct operational requirements, procurement cycles, and adoption drivers. Emergency care environments represent a primary demand vector, where rapid triage and objective decision support can reduce diagnostic uncertainty, optimize imaging utilization, and improve patient throughput. In parallel, sports medicine and athletic organization settings are increasingly adopting concussion assessment tools to support return-to-play protocols, mitigate liability exposure, and enhance athlete safety through data-driven clinical evaluation. Military and defense applications further contribute to market demand, where field-deployable and ruggedized diagnostic capabilities are valued for rapid injury assessment in austere environments and for supporting long-term neurological health surveillance. The interplay between these application segments creates a diversified demand base that insulates the market from single-sector volatility while simultaneously requiring manufacturers to tailor product specifications, validation evidence, and service models to distinct end-user expectations. Understanding the nuances of each demand channel is essential for companies designing go-to-market strategies, pricing architectures, and clinical education programs.
Traumatic Brain Injury Diagnostic Market
Worldwide Traumatic Brain Injuries Assessment And Management Devices Market
Market Structure and the Strategic Imperative of Evidence Generation
The current market structure reflects a sector in transition, where early adopters and clinical champions are validating new diagnostic workflows, and broader commercialization depends on the accumulation of robust clinical evidence, reimbursement alignment, and operational integration. The presence of multiple competing technological approaches means that differentiation is increasingly driven by clinical performance data, ease of workflow integration, and the ability to generate actionable prognostic insights rather than diagnostic confirmation alone. For strategic planners, this environment demands a disciplined focus on evidence generation timelines, health economics outcomes research, and real-world performance monitoring. Companies that can demonstrate clear clinical utility, cost-effectiveness, and seamless integration into existing care pathways are best positioned to convert regulatory clearance into sustained commercial traction. Conversely, organizations that underestimate the complexity of clinical adoption or fail to align product capabilities with measurable healthcare value may find market entry slower and more resource-intensive than projected.
Why This Report Matters for 2026 Strategic Decision-Making
As organizations plan capital allocation, product roadmaps, partnership strategies, and market entry initiatives for 2026 and beyond, access to granular, forward-looking market intelligence becomes a decisive competitive asset. This report delivers a structured, data-grounded analysis of the TBI diagnostic market across multiple dimensions: historical performance baselines, forecast trajectories, segment-level demand patterns, regional expansion dynamics, and competitive positioning frameworks. Beyond aggregate market sizing, the analysis provides actionable context for evaluating technology adoption curves, regulatory impact scenarios, and the commercial implications of emerging clinical evidence. It is designed to support executives in identifying high-probability growth corridors, assessing the relative strength of competitor portfolios, and anticipating shifts in procurement behavior across emergency, sports, and defense-related care settings. The report also includes detailed company profiles, recent development timelines, and strategic assessments that enable benchmarking of innovation pipelines, intellectual property positions, and commercialization readiness. By synthesizing macroeconomic growth indicators with operational and competitive intelligence, the research equips decision-makers with the contextual depth required to navigate uncertainty and align strategic investments with market realities.
Conclusion: Positioning for the Next Phase of Diagnostic Innovation
The traumatic brain injury diagnostic market stands at a pivotal juncture where technological innovation, regulatory validation, and clinical demand are converging to redefine how brain injuries are assessed, triaged, and managed. The projected growth trajectory, coupled with the expanding portfolio of biomarker assays, AI-enabled platforms, and point-of-care devices, signals a market that will reward strategic foresight, evidence-driven product development, and disciplined commercial execution. For organizations seeking to capture value in this evolving landscape, the difference between reactive participation and proactive leadership will increasingly depend on the quality of market intelligence guiding strategic choices. This report is structured to provide that intelligence, offering a comprehensive foundation for evaluating opportunities, anticipating competitive shifts, and building resilient strategies for the 2026 to 2032 horizon. To access the full dataset, detailed segment analyses, regional breakdowns, and complete competitive profiles, we invite you to explore the complete market research report.
For detailed analysis of this topic, please visit the official page: Traumatic Brain Injury Diagnostic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com